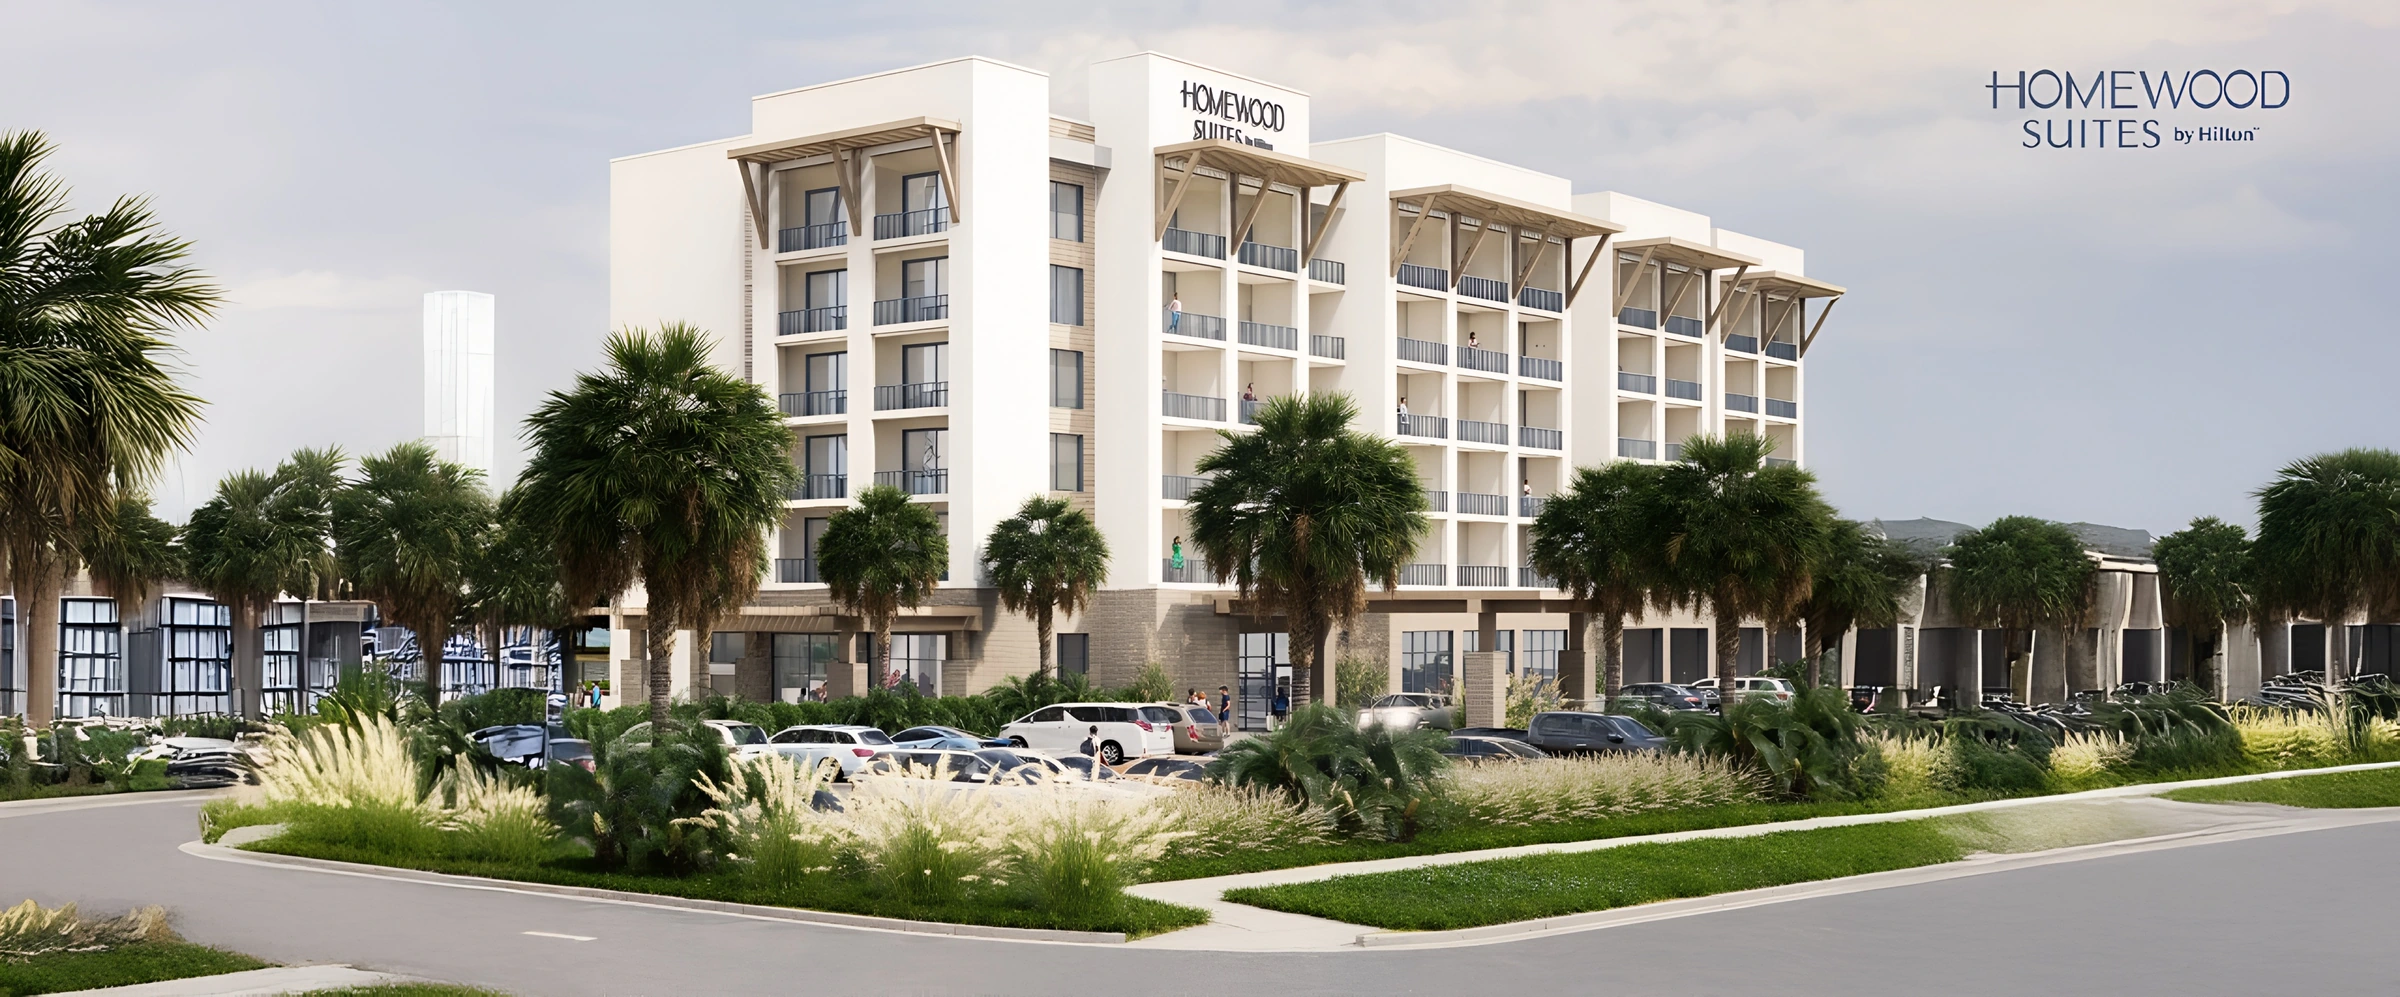
For many Brazilian investors, a house is the familiar entry point into U.S. real estate. Hospitality offers a different question: instead of owning only a property, what does it mean to participate in an operating business within that property? It can be compelling for some investors — but the current evidence does not justify calling it the best investment for everyone.
1. Why hotels are back in the conversation
CBRE’s midyear 2026 outlook connects improving fundamentals to domestic business travel, convention demand and constrained supply. Its scenario forecasts national RevPAR growth of 2.5% in 2026 and 2.1% in 2027, with occupancy of 62.8% and 63.0%, respectively. Those are industry estimates, not Singulys projections or returns available to an investor. Read the dated CBRE scenario ↗.
2. A “boom” is not the same for every hotel
The same CBRE scenario projects 2026 RevPAR growth of 5.2% for luxury hotels, 0.7% for midscale hotels and a 0.6% decline for economy hotels. This dispersion matters more than a broad slogan about tourism. A strong national market can coexist with weak local demand, excess nearby supply or an expensive development. A forecast for luxury hotels cannot simply be applied to an extended-stay project. Segment differences ↗.
3. Where hotel revenue actually comes from
The central source is room revenue: available rooms × nights in the period × occupancy × average daily rate. Depending on the property, additional revenue may come from food and beverages, parking, meeting space, events, laundry, retail and other paid services. Corporate accounts and group bookings are demand channels for these services, not separate revenue to count twice. Not every hotel has all these facilities; breakfast may be included in the rate rather than generating a separate charge.
4. More revenue does not necessarily mean more profit
Revenue must cover labor, distribution commissions, utilities, insurance, taxes, maintenance, management and franchise fees. Debt service, capital expenditures and reserves then affect available cash. HVS’s October 9, 2026 conference review reports that CoStar’s GOP margins through July were flat year over year despite RevPAR growth of about 5%. The message is important: a busier hotel can still fail to improve investor economics. HVS: revenue, margins and costs ↗.
5. What makes extended stay distinctive
Extended-stay hotels target guests staying longer: people relocating, project teams, temporary assignments and other local needs. Longer stays may reduce room turnover and some housekeeping and acquisition costs. That is an operating hypothesis to test, not a guaranteed margin. Kitchens, rate discounts, distribution, guest mix and local competitors also change the equation. A development requires its own feasibility study and evidence of demand at the intended price point.
6. How it differs from buying a rental house
A long-term rental house typically depends on rent, tenant retention and the property’s condition. It can offer a simpler operating model and direct ownership control, although taxes, insurance, repairs, vacancy and property management still matter. A hotel can spread room demand across many guests and adjust rates frequently, but has far greater operating intensity and more volatile demand. A vacation rental sits between these models: nightly pricing also brings seasonality, platform commissions, cleaning costs and local short-term rental restrictions. Neither comparison alone establishes a superior risk-adjusted return.
7. What the next few years may bring
CBRE’s midyear scenario expects hotel inventory growth of just 0.7% per year over the following three years, supporting its pricing thesis. It does not mean every market will lack new competitors. A more recent HVS October review describes stronger 2026 RevPAR expectations, near 5%, while stressing debt maturities, higher rates and persistent cost pressure. These are different forecasts and dates, not a consensus to average or a promise for 2027. Beyond the published horizons, evaluate scenarios rather than extrapolate a growth curve. CBRE midyear scenario ↗ · HVS October assessment ↗.
8. Do not compare RevPAR with home-price appreciation
RevPAR measures room revenue per available room, not property appreciation or an investor’s total return. A home-price index measures a different variable and excludes rental income and expenses. Fannie Mae publishes separate housing and mortgage forecasts; those can inform financing assumptions, but cannot be placed beside hotel revenue growth as if they were the same investment result. A fair comparison needs matching periods, leverage, taxes, fees, operating costs, capital spending, exit assumptions and currency effects. Fannie Mae: housing and mortgage research ↗.
9. The investor participates in a structure, not a headline
Buying an interest in a project vehicle is not the same as owning the building directly. Returns depend on the acquired participation, project-level debt, fund costs, sponsor rights, reserves and the distribution rules. Development adds permits, construction costs, timing and financing risk before the first guest arrives. Existing hotels bring operating history but may require renovations. There may be no ready market for a fund interest, and all invested capital can be lost.
10. The best starting point is your own plan
For investors able to evaluate operating risk, accept a long horizon and examine specific documents, hospitality may broaden the real-estate conversation beyond a single rental house. For someone who prioritizes direct control, simpler operations or near-term liquidity, another structure may be more suitable. The Singulys perspective is to start with your objectives, then examine the thesis — not declare a universal winner. Shall we have a coffee?
Different models. Different responsibilities.
| Dimension | Long-term rental house | Vacation rental | Hotel / project vehicle |
|---|---|---|---|
| Revenue | Contractual rent | Nightly / weekly stays | Room nights + services where offered |
| Pricing | Lease and renewal terms | Dynamic / seasonal | Dynamic by room and demand |
| Operations | Property and tenant management | Bookings, cleaning and platforms | Staff, distribution, brand and operator |
| Control | Direct owner decisions | Owner / property manager | Depends on participation and governance |
| Key risks | Vacancy, repairs, local prices | Seasonality and local restrictions | Operations, debt, costs, execution |
| Liquidity | Sale subject to the property market | Sale subject to the property market | May be highly restricted by vehicle terms |
Compare net, like-for-like investor economics — not a hotel revenue metric with a house price index.
Shall we have a coffee?
Explore the Singulys perspective and get in touch with our team.